And Why We Shouldn’t Fear the Ultra-Rich Leaving
Whenever the conversation turns to taxing the ultra-rich, a familiar panic sets in: If we tax our billionaires, they will pack up and leave!
The Federal NDP, spearheaded by figures like Avi Lewis, recently launched a petition urging Prime Minister Carney to implement a wealth tax. The proposal is surprisingly modest: an annual tax starting at just 1% on net worths over $10 million, scaling up to 3% for the very richest. Under this plan, 99.4% of Canadians would pay absolutely nothing; the burden falls exclusively on the wealthiest 0.6%.
To grasp the necessity of this policy, one must look at the staggering scale of Canadian inequality. According to Oxfam Canada’s 2026 Wealth Inequality Report, the richest 1% in Canada hoard nearly $3.9 trillion in wealth—an amount nearly equal to the combined wealth of the bottom 80% of the population.
The NDP projects this tax could raise $40 billion annually, compounding to $500 billion over a decade. That revenue represents a transformative nest egg that could help build one million non-market homes, make massive nation-building investments in public healthcare, and provide capital to launch a network of 50 public grocery stores.
Yet, opponents always circle back to the same existential dread about driving away “our billionaires.” This raises a fundamental question:
Just how necessary are billionaires to Canada?
We have been conditioned to view the ultra-wealthy as indispensable “job creators.” In reality, billionaires do not independently generate wealth; they accumulate it. A billion-dollar fortune is built on Canadian infrastructure, public education, healthcare, and the consumer spending of working people. An economy thrives on the velocity of money—when working people have cash, they spend it in their communities. When wealth is instead siphoned to the top and locked in massive stock portfolios, it starves the real economy.
Read also: When Machines Do the Work, Who Gets Paid?
But what about the threat of an exodus?
Recent empirical data proves the “billionaire flight risk” is vastly overstated. A landmark October 2026 study published in the American Economic Review examined administrative data from Scandinavian countries to measure migration responses to wealth taxes. The researchers found that a 1-percentage-point increase in the top wealth tax rate reduced overall employment by a microscopic 0.02% and economic value added by just 0.10%. The catastrophic economic damage threatened by anti-tax lobbyists simply does not materialize.
Furthermore, the logistics of fleeing Canada to dodge taxes make it a highly unpalatable, intensely expensive ordeal:
- The Departure Tax: The Canada Revenue Agency (CRA) does not let the ultra-rich simply walk away. When a billionaire cuts ties, they face a “deemed disposition,” meaning the CRA taxes the unrealized capital gains on their assets as if they had sold everything that very day. For example, if a founder leaves with $1 billion in company shares they built from scratch, their taxable profit is nearly the full billion. At top Canadian capital gains rates, this instantly triggers a departure tax bill of over $250 million. While individuals can legally defer payment of this massive bill until they actually sell the assets, doing so requires providing acceptable security (such as bank guarantees or liens on Canadian assets) directly to the CRA. The tax hangs over their head indefinitely.
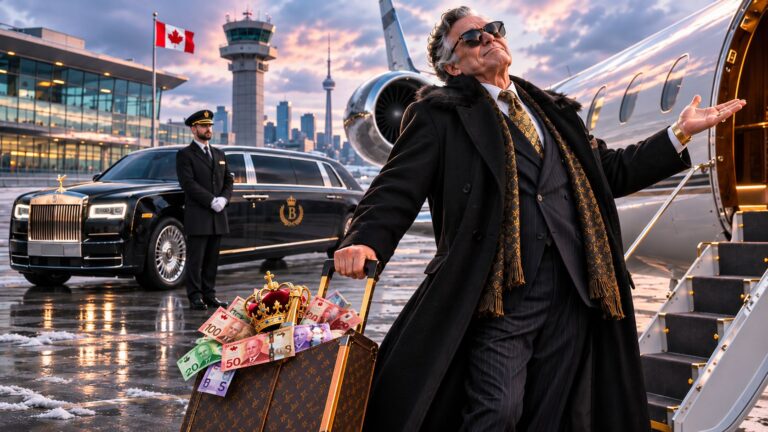
- The Reality of Severing Ties: We assume billionaires with private jets can easily live anywhere. But escaping Canadian tax residency is not as simple as changing your address. The CRA looks closely at the life you leave behind, including your Canadian homes, spouse, dependants, and even your memberships in social and recreational clubs. Those elite networks and institutions that help maintain a billionaire’s influence can serve as evidence that Canada is still their home. While no single club membership or business connection automatically makes someone a tax resident, the stronger the ties they maintain, the harder it may be to convince the CRA that they have genuinely left. They can take their money abroad, but maintaining the lifestyle, connections, and influence they enjoyed in Canada while claiming to live elsewhere is not necessarily so simple.
- Where Can They Go?: The most desirable relocation destinations, like the US or the UK, levy their own massive inheritance and estate taxes—often up to 40% (though subject to specific exemptions). If they instead flee to a “pure” zero-tax haven to dodge the CRA, they force themselves into financial exile. You cannot successfully run a multinational, billion-dollar empire if your corporate assets and bank accounts are constantly at risk of seizure the moment you try to move money through Wall Street, acquire property in Europe, or expand operations in treaty-cooperative countries.
Non-Payment of Taxes
When I was posting about this on social media, someone asked me this question:
“But what if they just refuse to pay the ‘exit’ tax? Why would a company pay a tax to leave? I wouldn’t. Canada can’t touch my money if it’s not in Canada.”
It sounds like a foolproof loophole, but it relies on a massive misconception about international tax law.
First, Canada doesn’t operate in a vacuum. We have heavy-duty tax treaties with almost every place a billionaire actually wants to live—including the US and the UK. Under the Canada-US Tax Convention, the IRS can legally assist the CRA in collecting established tax debts. While not automatic, the mechanism exists for foreign governments to target an expatriate’s assets on Canada’s behalf.
Second, billionaire wealth is tied up in physical Canadian businesses, real estate, and corporate shares. If a billionaire attempts to ghost the CRA on their personal tax debts, the government has the legal authority to register liens, garnish income, and seize their personal shares and Canadian assets to satisfy the debt. You cannot easily maintain control of a Canadian business empire while refusing to pay the Canadian government.
Finally, naysayers will inevitably point to a different hurdle:
Domestic tax loopholes
They argue that billionaires won’t leave; their accountants will just use complex trusts and holding companies to hide their net worth. This is a valid concern—the current tax code is littered with provisions that disproportionately benefit the ultra-wealthy. But this is exactly why a modern wealth tax cannot simply be dropped onto the existing, leaky system. It must be written with aggressive, ironclad anti-avoidance measures built in from day one. Closing these escape hatches isn’t a pipe dream; it is a basic requirement of the legislation.
Ultimately, escaping a wealth tax requires legally and financially uprooting an entire empire, facing steep departure taxes, and navigating complex international tax enforcement. The threat of a billionaire exodus is a hollow bluff designed to protect the status quo. It is time to stop catering to the fears of the 0.6% and start investing in the 99.4% who actually keep the country running.
Note: Irrespective of being an NDP supporter or not, if you agree with a tax on the uber-wealthy, sign the petition: https://www.ndp.ca/take-action/wealth-tax-now/
About The Author